
 +91-22-48913909
Systematic Withdrawal Plan (SWP): Meaning, How It Works & Benefits
What if your money could stay invested while you withdraw a fixed amount from it every month?
That is the basic idea behind a Systematic Withdrawal Plan (SWP). Instead of withdrawing your entire mutual fund investment at once, you can set up regular withdrawals from your corpus at intervals such as monthly or quarterly.
For someone planning retirement, funding regular expenses or creating a structured cash-flow plan, an SWP can be a useful way to access an existing mutual fund investment. But there is an important catch: an SWP does not guarantee income, protect your capital or eliminate market risk. The outcome depends on the mutual fund, withdrawal amount, market performance and how long the corpus needs to last.

So, which Mutual Funds can be considered for an SWP, how much can you withdraw, and what happens to your investment when markets fall?
This guide explains how SWP works, the mutual fund categories investors may consider, how to choose a fund, SWP risks, taxation and how to estimate withdrawals using an SWP Calculator.
What is a Systematic Withdrawal Plan (SWP)?
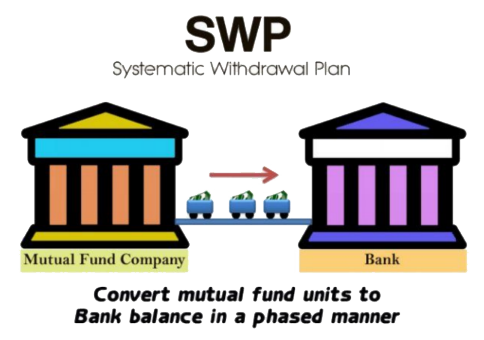
A Systematic Withdrawal Plan (SWP) is a mutual fund facility that allows investors to withdraw a fixed amount or a specified number of units from their investment at regular intervals. Depending on the scheme and available options, withdrawals can generally be scheduled monthly, quarterly or at another chosen frequency.
Unlike a SIP, where money is regularly invested into a mutual fund, an SWP involves redeeming units from an existing investment. The remaining units stay invested and continue to be affected by the performance of the underlying mutual fund.
For example, suppose you have ₹10 lakh invested in a mutual fund and set up an SWP of ₹20,000 per month. The fund will redeem the number of units required to provide ₹20,000 based on the applicable NAV. The remaining units continue to stay invested.
Importantly, an SWP does not guarantee a fixed return or protect the invested corpus. If the underlying fund falls in value, more units may need to be redeemed to meet the same withdrawal amount. Therefore, the choice of fund, withdrawal amount, investment horizon and market conditions can all affect how long the corpus lasts.
In simple terms:
- SIP → Money goes into the mutual fund regularly
- SWP → Money comes out of the mutual fund regularly
How Does an SWP Work?
An SWP allows you to withdraw money from an existing mutual fund investment at regular intervals without redeeming the entire investment at once.
The amount you receive through each withdrawal depends on the number of units redeemed and the applicable NAV (Net Asset Value) on the redemption date.
Example
Suppose you have ₹10 lakh invested in a mutual fund and set up a monthly SWP of ₹20,000.
- If the NAV is ₹100, ₹20,000 would require redemption of 200 units.
- If the NAV falls to ₹80, the same ₹20,000 withdrawal would require 250 units.
- If the NAV rises to ₹125, the withdrawal would require 160 units.
The remaining units continue to stay invested after each withdrawal.
This means the number of units redeemed can change from one withdrawal to another as the NAV changes. An SWP does not guarantee that the investment will continue to grow or that the original corpus will remain intact.
What Determines How Long Your Corpus Lasts?
The sustainability of an SWP can depend on:
- Initial investment corpus
- Withdrawal amount
- Withdrawal frequency
- Performance of the underlying mutual fund
- Market conditions
- Investment horizon
- Taxes and applicable costs
Therefore, choosing an SWP is not simply about finding a fund with the highest past return. The withdrawal requirement and the investor's risk tolerance also need to be considered.
Talk to our investment specialist
Why Do Investors Use an SWP?
An SWP can help investors turn an existing mutual fund corpus into a structured stream of withdrawals. It can be useful when an investor needs regular cash flow but does not want to redeem the entire investment at once.
1. Regular Cash Flow
Investors can set up withdrawals at a chosen frequency, such as monthly or quarterly, depending on the options available under the mutual fund scheme. This can help meet planned expenses from an existing investment corpus.
2. Disciplined Withdrawals
Instead of making ad-hoc redemptions whenever money is required, an SWP creates a predefined withdrawal schedule. This can help investors follow a structured withdrawal plan.
3. Flexibility
The withdrawal amount and frequency can generally be selected based on the investor's requirements and the options offered by the scheme. An SWP can also be modified or stopped, subject to the scheme's terms.
4. Remaining Corpus Stays Invested
An SWP does not require the entire mutual fund investment to be redeemed at once. Only the units required to meet each withdrawal are redeemed, while the remaining units continue to stay invested and remain exposed to market movements.
Important: An SWP does not guarantee regular returns, protect the principal or ensure that the investment will last for a specific period. The sustainability of the corpus depends on factors such as the withdrawal amount, investment performance, market conditions and investment horizon.
SIP vs SWP
SIP and SWP are often discussed together, but they serve opposite purposes. A SIP is generally used to invest money into a mutual fund at regular intervals, while an SWP is used to withdraw money from an existing mutual fund investment at regular intervals.
| Feature | SIP | SWP |
|---|---|---|
| Full form | Systematic Investment plan | Systematic Withdrawal Plan |
| Purpose | Regular investment | Regular withdrawal |
| Cash flow | Money goes into the mutual fund | Money comes out of the mutual fund |
| How it works | Purchases units at regular intervals | Redeems units at regular intervals |
| Common use | Building an investment corpus | Creating planned cash flow from a corpus |
| Market exposure | Investment remains market-linked | Remaining investment remains market-linked |
Simple example
If you invest ₹10,000 every month into a mutual fund, you are using a SIP. If you already have a mutual fund corpus and withdraw ₹10,000 every month from it, you are using an SWP. Neither SIP nor SWP guarantees returns. The appropriate approach depends on your investment objective, financial situation, risk tolerance and time horizon.
Mutual Fund Categories to Consider for SWP
There is no separate “SWP mutual fund” category. SWP is a withdrawal facility that can be used with eligible mutual fund schemes. The suitable fund category depends on how long you need the withdrawals, how much market Volatility you can accept and how much of your corpus you need to withdraw.
1. Liquid Funds
Liquid Funds invest in short-term money market and debt instruments. They may be considered when the priority is relatively lower volatility and short-term cash management. However, lower volatility does not mean zero risk or guaranteed returns.
2. Ultra Short Duration Funds
These funds invest in debt and money-market instruments with a relatively short Portfolio duration. They may be considered when you want regular withdrawals while keeping the investment horizon relatively short.
3. Hybrid Funds
Hybrid Fund invest across equity and debt in varying proportions. Depending on the specific category, they can offer a balance between growth potential and income-oriented stability. The level of market risk can differ significantly between hybrid categories, so the category and portfolio should be evaluated before Investing.
4. Equity Funds
Equity-oriented categories such as Large cap funds may be considered for longer-term SWP requirements where the investor is comfortable with market fluctuations. However, Equity Funds can experience substantial short-term declines. Using an SWP during a market downturn may require redeeming more units to generate the same withdrawal amount.
Which Category Should You Choose?
There is no single mutual fund category that is suitable for every SWP investor. Consider:
- Your investment horizon
- Monthly or quarterly withdrawal requirement
- Total corpus available
- Risk tolerance
- Need for capital stability
- Expected duration of withdrawals
- Tax implications
- Fund expenses and portfolio quality
The objective should be to match the fund's risk and investment strategy with your withdrawal needs, rather than choosing a fund simply because it has delivered high past returns.
How to Choose a Mutual Fund for SWP
Choosing a mutual fund for SWP is not simply about finding the fund with the highest past return. The fund should match your withdrawal needs, investment horizon and ability to handle market fluctuations.
1. Consider Your Investment Horizon
Start by asking how long you expect to continue the withdrawals. A short-term requirement may call for a different fund category than a long-term retirement corpus.
2. Match the Fund With Your Risk Tolerance
Equity-oriented funds can experience significant fluctuations, while some debt-oriented categories may have relatively lower volatility. Choose a category whose risk you can reasonably handle during market declines.
3. Evaluate Your Withdrawal Requirement
Consider how much you need to withdraw and how frequently. A higher withdrawal relative to the corpus can put greater pressure on the investment, particularly during periods of weak market performance.
4. Look Beyond Past Returns
Past returns can provide useful information, but they should not be the sole selection criterion. Also consider:
- Consistency of performance
- Volatility and downside risk
- Portfolio composition
- Expense ratio
- Fund strategy and category
- Fund size and liquidity, where relevant
5. Consider Market Conditions
An SWP continues to redeem units regardless of whether markets are rising or falling. During a market decline, the same withdrawal amount may require the redemption of more units.
6. Review the Corpus and Withdrawal Plan Together
The suitability of an SWP depends not only on the mutual fund but also on the starting corpus, withdrawal amount, withdrawal frequency and expected duration.
Important: There is no universally applicable “safe” SWP amount or withdrawal rate. An amount that may be sustainable for one investor may not be suitable for another. Use the SWP calculator as an estimate and review the plan periodically.
What Happens to an SWP During a Market Downturn?
An SWP does not stop when the market falls. Your scheduled withdrawal continues, which means the number of mutual fund units redeemed can increase when the NAV declines.
For example, suppose you withdraw ₹20,000 every month:
- At a NAV of ₹100 → 200 units are redeemed
- At a NAV of ₹80 → 250 units are redeemed
- At a NAV of ₹125 → 160 units are redeemed
This means a market downturn can have a greater impact on the remaining corpus if withdrawals continue while the investment value is falling.
Why Does This Matter?
If a large number of units are redeemed during a prolonged market decline, fewer units remain invested when markets eventually recover. This can affect the longevity of the corpus.
The impact depends on several factors, including:
- Starting investment corpus
- Withdrawal amount
- Frequency of withdrawals
- Fund performance
- Duration of the downturn
- Overall investment horizon
Therefore, when setting up an SWP, it is important to consider both the withdrawal requirement and the underlying fund's risk, rather than looking only at past returns.
An SWP can provide a structured withdrawal mechanism, but it does not protect the corpus from market losses or guarantee that the investment will last for a particular period.
How Much Can You Withdraw Through an SWP?
There is no single withdrawal amount that works for every investor. The amount you can withdraw through an SWP depends on your investment corpus, withdrawal frequency, fund performance, market conditions and the period for which you need the money.
For example, an investor with a ₹20 lakh corpus and an investor with a ₹1 crore corpus may have very different withdrawal requirements and sustainability.
Before setting up an SWP, consider:
- Total investment corpus
- Monthly or quarterly withdrawal requirement
- Expected duration of withdrawals
- Risk and volatility of the chosen fund
- Expected returns, without assuming they are guaranteed
- Taxes and other applicable costs
- Whether withdrawals may need to increase over time
Can You Withdraw a Fixed Amount Every Month?
Yes. An SWP can generally be set up for a specified amount at regular intervals, subject to the mutual fund scheme's terms. However, a fixed withdrawal amount does not mean a fixed return. The amount withdrawn is generated by redeeming units from your investment. If the NAV falls, more units may need to be redeemed to generate the same withdrawal.
Use an SWP Calculator
An SWP calculator can help estimate how your corpus may change based on:
Initial Investment + Expected Return + Withdrawal Amount + Withdrawal Frequency + Investment Duration
The result is only an illustration based on the assumptions entered. Actual returns can vary because mutual fund returns are market-linked. Before deciding on a withdrawal amount, consider whether the projected withdrawals are compatible with your corpus, investment horizon and risk tolerance.
Want to see how SWP can work for you? Use our SWP Calculator now to plan your withdrawals and estimate your returns. Start making informed investment decisions today!
VALUE AT END OF TENOR:₹4,597SWP Calculator
Taxation of Systematic Withdrawal Plans (SWP) in India
An SWP is a facility that allows investors to withdraw money from an existing mutual fund investment at regular intervals. Each withdrawal involves the redemption of mutual fund units. Therefore, tax is generally applicable to the capital gain arising on the units redeemed, rather than automatically on the entire withdrawal amount. The applicable tax treatment depends on the type of mutual fund, acquisition date of the units, holding period and relevant Capital Gains provisions.
1. How Is an SWP Taxed?
Suppose you invest ₹1 lakh in a mutual fund and later withdraw ₹10,000 through an SWP. The entire ₹10,000 is not necessarily taxable as a capital gain. The units redeemed have an acquisition cost, and the difference between their acquisition cost and redemption value determines the capital gain or loss.
Since an SWP involves periodic redemptions, different withdrawals may have different tax implications depending on the units redeemed and their respective holding periods.
2. Taxation of Equity-Oriented Mutual Funds
For equity-oriented mutual funds that meet the applicable conditions:
- Short-Term Capital Gains (STCG): Gains on units held for 12 months or less are generally taxed at 20%.
- Long-Term Capital Gains (LTCG): Gains on units held for more than 12 months are generally taxed at 12.5%.
- Under Section 112A, eligible long-term capital gains up to ₹1.25 lakh in aggregate in a financial year are covered by the applicable threshold, subject to the prescribed conditions.
Therefore, the earlier rates of 15% STCG and 10% LTCG in the older version of this article should not be used for current transactions.
3. Taxation of Debt Mutual Funds
Taxation of debt-oriented mutual funds depends on the scheme's characteristics and the date on which the units were acquired.
Certain specified mutual funds are subject to special provisions under Section 50AA. Therefore, the earlier blanket explanation that debt mutual funds held for more than three years are taxed at 20% with indexation should not be used as a general rule for current investments.
Investors should check whether Section 50AA or other applicable provisions apply to the particular mutual fund and the units being redeemed.
4. Does Every SWP Withdrawal Have the Same Tax Treatment?
Not necessarily.
If you have made multiple investments or SIP instalments, the units redeemed through different SWP withdrawals may have different:
- Purchase dates
- Acquisition costs
- Holding periods
- Capital gains or losses
Therefore, the tax treatment should be determined based on the specific units redeemed, rather than simply considering how long the overall mutual fund investment has existed.
5. SWP and Dividends Are Different
An SWP and a dividend/distribution are two different mechanisms. An SWP involves the redemption of mutual fund units, whereas a dividend/distribution is paid separately when declared by the mutual fund scheme. Therefore, dividend taxation should not be presented as part of SWP taxation. The earlier reference to Dividend Distribution Tax (DDT) should also be removed.
Example of SWP Taxation
Suppose you invest ₹1,00,000 in an equity-oriented mutual fund and later redeem units worth ₹5,000 through an SWP. If the acquisition cost of those particular units is ₹4,000, the capital gain is ₹1,000, not ₹5,000.
The applicable tax treatment would then depend on whether those units qualify as short-term or long-term and the relevant capital gains provisions.
Important: Tax rules can change. Investors should verify the applicable provisions for the relevant financial year and consider professional tax advice where required.
Who Should Consider an SWP?
An SWP may be considered by investors who already have a mutual fund corpus and want to withdraw money at regular intervals while keeping the remaining investment invested. It may be relevant for:
1. Investors Seeking Regular Cash Flow
Investors who need periodic withdrawals for expenses may use an SWP to create a structured withdrawal schedule.
2. Retirees With an Investment Corpus
Retirees may consider an SWP as one component of their overall cash-flow planning, depending on their corpus, expenses, risk tolerance and other sources of income.
3. Investors With a Long-Term Withdrawal Requirement
An SWP can be structured over an extended period, but the sustainability of withdrawals depends on the corpus, withdrawal rate, fund performance and market conditions.
4. Investors Who Want Flexible Withdrawals
Depending on the scheme's terms, investors may be able to modify the withdrawal amount or frequency or stop the SWP when their requirements change.
Important Consideration
An SWP is not suitable simply because an investor wants regular income. Before setting one up, consider whether the underlying fund's risk level, the withdrawal amount and the investment horizon are aligned with your financial needs. An SWP does not guarantee regular returns, capital protection or that the corpus will last for the entire withdrawal period.
Retirement Planning Using SWP
Retirement often brings a different financial challenge: how to generate regular cash flow from a corpus that has already been built. A Systematic Withdrawal Plan (SWP) can be one way to structure these withdrawals from a mutual fund investment. Under an SWP, a specified amount is withdrawn periodically by redeeming mutual fund units, while the remaining units continue to stay invested.
For example, a retiree with an existing mutual fund corpus may set up a monthly SWP to meet regular expenses. The withdrawal amount and frequency can generally be selected according to the scheme's applicable terms.
SWP vs Traditional Retirement Income Options
One feature of an SWP is flexibility. Depending on the scheme and platform, investors may be able to modify or stop the withdrawal instruction and redeem their remaining units, subject to applicable terms.
However, an SWP differs from products such as Senior Citizen Savings Scheme (SCSS) or Post Office Monthly Income Account in structure and risk. Mutual fund investments are market-linked, whereas small-savings schemes operate under their own government-prescribed rules.
With an SWP, the remaining corpus stays invested and its value can rise or fall with the underlying mutual fund. Therefore, regular withdrawals do not guarantee a fixed income or preservation of the original corpus.
What Should Retirees Consider?
Before using an SWP for retirement income, consider:
- Size of the retirement corpus
- Monthly income requirement
- Investment horizon
- Risk tolerance
- Fund category and portfolio
- Withdrawal amount relative to the corpus
- Tax implications
- Other sources of retirement income
SWP can be a useful cash-flow tool, but it should be viewed as part of a broader retirement-income plan rather than as a guaranteed pension replacement.
Frequently Asked Questions About SWP
1. Is SWP the same as SIP?
A: No. A SIP involves investing money into a mutual fund at regular intervals, while an SWP involves withdrawing money from an existing mutual fund investment at regular intervals.
2. Does SWP guarantee monthly income?
A: No. An SWP provides a scheduled withdrawal facility, but it does not guarantee investment returns or protect the invested capital.
3. Can I change or stop my SWP?
A: Generally, yes, subject to the mutual fund scheme's terms and the platform through which the SWP is set up. Investors can typically modify or stop the withdrawal instruction when required.
4. Can I use an SWP with an equity mutual fund?
A: Yes. SWP is a withdrawal facility and is not restricted to a particular mutual fund category. However, equity funds can experience significant market fluctuations, which should be considered when planning regular withdrawals.
5. What happens if the market falls during an SWP?
A: The same withdrawal amount may require more units to be redeemed when the NAV is lower. Continued withdrawals during a prolonged downturn can therefore reduce the remaining number of units more quickly.
6. Is SWP suitable for retirement planning?
A: An SWP may form part of a retirement cash-flow strategy for some investors. Its suitability depends on factors such as the total corpus, withdrawal requirement, investment horizon, risk tolerance and other sources of income.
7. Is the entire SWP withdrawal taxable?
A: Not necessarily. Tax treatment generally relates to the capital gain arising from the units redeemed, rather than automatically treating the entire withdrawal as a taxable capital gain. The applicable rules depend on the scheme and the relevant tax provisions.
8. How much should I withdraw through an SWP?
A: There is no universal withdrawal amount that is suitable for everyone. Consider your corpus, withdrawal requirement, expected duration, fund risk and market conditions before deciding on an amount.
9. Can I start an SWP immediately after investing?
A: The availability of an SWP and any minimum holding period or other conditions can depend on the mutual fund scheme and its terms. Check the scheme's applicable conditions before setting up the withdrawal.
10. Does SWP protect my mutual fund corpus?
A: No. The remaining corpus continues to be exposed to the performance and risks of the underlying mutual fund. Regular withdrawals can also reduce the corpus over time.
Conclusion
A Systematic Withdrawal Plan (SWP) can help investors create a structured cash flow from an existing mutual fund corpus without redeeming the entire investment at once. However, an SWP is not a guaranteed income or capital-protection strategy. The sustainability of withdrawals depends on factors such as the initial corpus, withdrawal amount, fund performance, market conditions, investment horizon and applicable taxes.
Before starting an SWP, evaluate the underlying mutual fund, your withdrawal requirement and your ability to handle market fluctuations. Review the withdrawal plan periodically as your financial needs and market conditions change.
The right SWP is not simply about withdrawing the highest amount. It is about creating a withdrawal plan that is aligned with your financial needs, investment horizon and risk tolerance.
All efforts have been made to ensure the information provided here is accurate. However, no guarantees are made regarding correctness of data. Please verify with scheme information document before making any investment.




AMFI Registration No. 112358 | CIN: U74999MH2016PTC282153
Shepard Technologies Pvt. Ltd. (with ARN code 112358) makes no warranties or representations, express or implied, on products offered through the platform. It accepts no liability for any damages or losses, however caused, in connection with the use of, or on the reliance of its product or related services. Terms and conditions of the website are applicable.
©2026 Shepard Technologies Private Limited. All Rights Reserved
It is very helpful for understanding the Systematic withdrawal plan. Systematic withdrawal plan is very useful for raising the fund.