
 +91-22-48913909
Mutual Fund Investment Guide: How to Invest in Mutual Funds
Mutual Fund Investment Guide: Where Should You Start?
You don't need to know everything about the stock market before Investing in a mutual fund. But you do need to know why you are investing, how much risk you can take and what type of mutual fund fits your goal.
That's where things can get confusing.
Should you start with a SIP or invest a lump sum? Should you choose an equity fund, debt fund or Hybrid Fund? What does NAV mean? Is a direct plan better than a regular plan? And how do you know whether a fund is actually suitable for you? This mutual fund investment guide takes you through these decisions in a simple, practical order.
The goal is not to find the fund with the highest recent return. It is to understand how to make a mutual fund investment decision that fits your financial situation.
What Is a Mutual Fund?
A mutual fund pools money from multiple investors and invests it in a portfolio of securities according to the scheme's investment objective. Depending on the scheme, the portfolio may invest in equities, debt and money-market instruments or other permitted securities.
When you invest, you receive mutual fund units. The value of your investment changes with the value of the underlying portfolio and the applicable NAV. Mutual fund schemes in India are regulated by the Securities and Exchange Board of India (SEBI). The Association of Mutual Funds in India (AMFI) is the industry association that provides investor education and industry information. AMFI India
The important thing to remember is that not all mutual funds carry the same level of risk. An equity fund, a liquid fund, a small-cap fund and a hybrid fund can have very different investment objectives and risk profiles.
So, choosing a mutual fund should begin with your goal and risk profile, not with a search for the highest return.
How to Start Investing in Mutual Funds
Starting a mutual fund investment does not have to be complicated. A simple process can help you avoid choosing a scheme first and figuring out its purpose later.
1. Define Your Investment Goal
Start with the question: What am I investing for?
Your goal could be:
- Building long-term wealth
- retirement
- Buying a home
- Children's education
- A future financial requirement
- A medium-term goal
- General wealth creation
The goal helps determine your investment horizon and the type of risk you may be able to take. For example, money required for a near-term goal may need a very different approach from money being invested for a 15-year retirement goal.
Talk to our investment specialist
2. Decide Your Investment Horizon
Your investment horizon is the period for which you expect to remain invested. Think in terms of:
- Short term
- Medium term
- Long term
Do not choose a fund category simply because it has performed well recently. The investment horizon should be compatible with the risk and characteristics of the fund. Equity-oriented funds can experience significant short-term volatility and are generally considered more suitable for investors who can tolerate market fluctuations and have a longer investment horizon. AMFI India
3. Understand Your Risk Profile
Risk profiling involves understanding both your ability and willingness to take investment risk. Two investors with the same income may have very different risk profiles.
Consider:
- How much loss can you financially absorb?
- How would you react if your investment fell temporarily?
- When will you need the money?
- Do you have other investments?
- Is the investment essential for an upcoming goal?
Mutual funds carry different levels of risk, and SEBI's Riskometer is designed to help investors understand the risk level of a scheme. Securities and Exchange Board of India
4. Decide Your Asset Allocation
Asset Allocation means deciding how your investments are distributed across different asset classes. Depending on your financial situation, this could involve combinations of:
- Equity
- Debt
- Gold or other permitted assets
- Cash or cash equivalents
There is no single asset allocation that is suitable for everyone. A young investor with a long investment horizon may have a different allocation from someone approaching retirement.
5. Choose the Mutual Fund Category
Once you understand your goal, horizon and risk profile, choose the category that fits your requirement. This is an important step. Do not start by comparing 20 fund names. Start by deciding what type of fund you need.
6. Compare Funds Within the Category
Only after selecting an appropriate category should you compare individual schemes. Look at factors such as:
- Investment objective
- Consistency of performance
- Risk and volatility
- Portfolio composition
- Expense ratio
- Fund strategy
- Fund manager and investment process
- AUM and liquidity, where relevant
- Exit load and other applicable costs
Past performance can provide useful context, but it does not guarantee future returns.
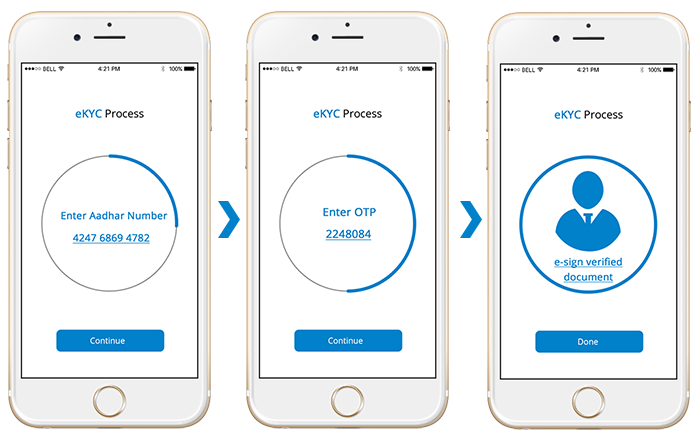
7. Complete KYC and Invest
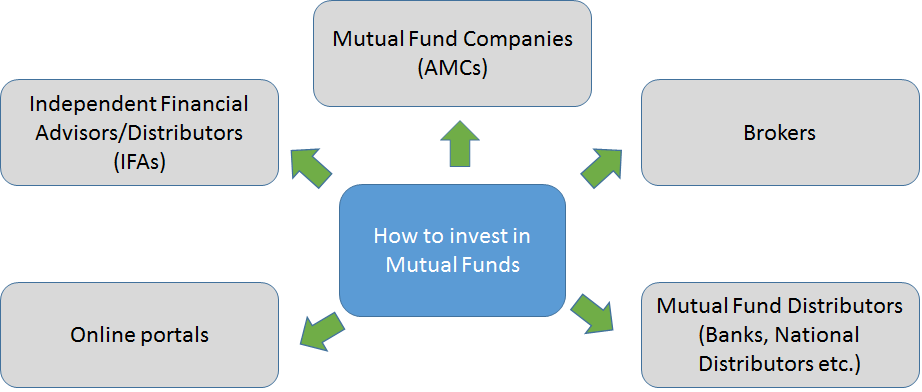
Investors need to meet applicable KYC requirements before investing in mutual funds. Depending on the route you choose, investments can be made through:
- An AMC's platform
- A registered mutual fund platform
- A distributor or financial intermediary
- Other permitted investment channels
Always verify the platform, scheme details and transaction information before investing.
Open Free Investment Account for Lifetime at Fincash.com. Get Started
Types of Mutual Funds in India
Mutual fund schemes can be classified in several ways. AMFI's scheme classification broadly includes equity, debt, hybrid, solution-oriented and other schemes, with further sub-categories within these groups. AMFI India
Here is a simple overview -
1. Equity Mutual Funds
Equity Funds predominantly invest in equities and equity-related instruments. Examples include:
- Large cap funds
- mid cap funds
- Small cap funds
- Flexi Cap Funds
- Multi Cap Funds
- ELSS
- Sectoral/thematic funds
- value funds
- contra funds
Equity funds can offer long-term growth potential but can also experience significant market fluctuations.
2. Debt Mutual Funds
Debt funds invest predominantly in fixed-income and money-market instruments. The category includes schemes such as:
- Liquid Funds
- Overnight Funds
- Ultra Short Duration Funds
- Short Duration Funds
- Corporate bond Funds
- Banking & PSU Debt Funds
- Gilt Funds
- Dynamic Bond Funds
- Credit Risk Funds
Debt funds are not risk-free. Risks can include interest-rate risk, credit risk and liquidity risk, depending on the scheme.
3. Hybrid Mutual Funds
Hybrid funds invest in a combination of equity and debt, with the allocation depending on the specific category. Examples include:
- Conservative Hybrid Funds
- Balanced Hybrid Funds
- Aggressive Hybrid Funds
- Dynamic Asset Allocation/Balanced Advantage Funds
- Multi Asset Allocation Funds
- Arbitrage Funds
- Equity Savings Funds
The level of equity exposure can significantly affect the risk profile of a hybrid fund. AMFI India
4. Solution-Oriented Funds
These schemes are designed around specific long-term objectives, such as:
- Retirement
- Children's financial goals
The specific scheme characteristics and applicable conditions should be checked before investing.
5. Index Funds
Index Funds are passively managed mutual funds that seek to track a particular market index. For example, an index fund may seek to replicate the performance of an index such as the Nifty 50 or Sensex, subject to tracking error and expenses. The objective is generally to track the index rather than actively select stocks to outperform it.
6. Exchange-Traded Funds (ETFs)
ETFs are traded on stock exchanges like securities during market hours. They can track an index or provide exposure to other permitted assets. Unlike a conventional mutual fund purchase, buying and selling an ETF generally takes place through a Trading Account and exchange mechanism.
How to Choose the Right Mutual Fund
There is no universally “best” mutual fund. A fund that is suitable for one investor may be completely unsuitable for another. Use this framework before selecting a scheme.
1. Start With the Goal
A retirement investment, emergency reserve and five-year financial goal may require different approaches.
2. Match the Category With Your Horizon
Do not choose a fund category first and then try to fit your goal around it.
3. Check the Risk
Look at the scheme's Riskometer, portfolio and underlying risks rather than relying only on a return number. Securities and Exchange Board of India
4. Look at Consistency
Instead of asking: “Which fund gave the highest return last year?”
Ask: “How has this fund performed across different market conditions?”
5. Understand the Portfolio
Check where the fund invests and whether the portfolio aligns with the scheme's stated objective.
6. Check the Expense Ratio
The expense ratio represents the recurring expenses charged to the scheme. Even seemingly small differences in costs can matter over long periods because investment returns compound over time.
7. Understand the Fund's Strategy
Read the scheme's investment objective and understand how the fund manager intends to implement it.
8. Check Exit Load and Other Costs
Some schemes may charge an exit load if units are redeemed within a specified period. Read the applicable scheme documents before investing.
SIP vs Lump Sum: Which Is Better?
Both SIP and lump-sum investing are ways to invest in Mutual Funds. They are not separate Types of Mutual Funds.
SIP
A Systematic Investment Plan (SIP) allows you to invest a specified amount at regular intervals, subject to the scheme and platform terms. SIPs can help investors build an investment habit and spread purchases across different market levels.
Lump Sum
A lump-sum investment involves investing a larger amount at one time. This means the money is exposed to market movements from the time it is invested.
Which Should You Choose?
The answer depends on your circumstances.
| SIP | Lump Sum |
|---|---|
| Invests periodically | Invests a larger amount at one time |
| Useful for regular income | Useful when you already have investible capital |
| Helps create investment discipline | Gives immediate market exposure |
| Purchases units at different NAVs over time | Entire amount is invested at the prevailing applicable NAV |
SIP does not eliminate market risk, and lump-sum investing is not automatically better or worse. The choice should depend on your cash flow, goal, asset allocation and investment strategy.
Direct vs Regular Mutual Fund Plans
When investing in a mutual fund, you may come across Direct and Regular plans. Both plans belong to the same mutual fund scheme and generally have the same underlying portfolio and fund manager, but their expense structures differ.
Direct Plan
A Direct Plan is purchased directly without routing the investment through a distributor. It has a lower expense ratio because distributor commissions are not included in the plan's expenses. AMFI India
Regular Plan
A Regular Plan is purchased through a distributor or intermediary. The expense ratio is generally higher because it includes distribution-related costs.
Which One Should You Choose?
- A Direct Plan may suit an investor who is comfortable researching funds and managing investments independently.
- A Regular Plan may be relevant for an investor who wants the services or guidance of a distributor.
- Lower cost does not automatically mean better suitability. The important question is whether you can select and manage investments appropriately for your needs.
What Does a Mutual Fund Investment Cost?
The return you see from a mutual fund should not be considered without understanding its costs.
Expense Ratio
The expense ratio represents the recurring expenses charged to operate and manage the scheme. Because expenses affect the value of the investment over time, compare costs when evaluating similar schemes.
Exit Load
Some mutual funds charge an exit load when units are redeemed within a specified period. The applicable amount and conditions vary by scheme.
Other Applicable Costs
Depending on the transaction and scheme, other charges or taxes may apply. Always check the latest scheme documents and applicable regulations before investing.
What Is NAV in a Mutual Fund?
NAV stands for Net Asset Value. It represents the per-unit value of a mutual fund scheme based on the value of its net assets and the number of units outstanding, after applicable adjustments.
The NAV of an open-ended mutual fund changes as the value of its underlying portfolio changes. However, a lower NAV does not automatically mean a mutual fund is cheaper or better. Similarly, a higher NAV does not mean a fund is expensive.
When comparing funds, focus on the scheme's objective, portfolio, performance, risk, costs and suitability rather than the NAV alone.
How to Invest in Mutual Funds Online
Investing online can be straightforward once your KYC requirements are completed. A typical process is:
Step 1: Choose Your Investment Route
You can invest through an AMC, registered platform, distributor or another permitted channel.
Step 2: Complete KYC
Complete the applicable KYC process and provide the required information.
Step 3: Select the Scheme
Choose the mutual fund category and scheme based on your investment objective and risk profile.
Step 4: Choose SIP or Lump Sum
Decide whether you want to invest periodically or invest an available lump sum.
Step 5: Select Direct or Regular Plan
Choose the plan based on whether you want to invest independently or through a distributor.
Step 6: Complete the Transaction
Follow the platform's payment and authentication process.
Step 7: Review Your Investment
After investing, keep track of your portfolio and review it periodically rather than reacting to every short-term market movement.
Open Free Investment Account for Lifetime at Fincash.com. Get Started
How to Review Your Mutual Fund Portfolio
Investing is not the end of the process. Your financial goals, income, risk tolerance and investment horizon can change over time. A portfolio review can help you check:
- Whether your asset allocation is still appropriate
- Whether the funds still match your goals
- Whether your risk level has changed
- Whether your portfolio has become overly concentrated
- Whether your investment strategy remains consistent
- Whether a fund's objective or strategy has materially changed
Review does not mean constantly buying and selling. A good review asks whether your investments are still doing the job they were chosen to do.
Common Mutual Fund Investment Mistakes
1. Chasing the Highest Recent Return
A fund that topped the return chart last year may not do the same in the future.
2. Choosing a Fund Without a Goal
Without knowing why you are investing, it becomes difficult to determine the appropriate horizon and risk level.
3. Ignoring Risk
Higher return potential generally comes with greater uncertainty. Never judge a fund by return alone.
4. Investing Only Because Someone Recommended It
A fund that works for a friend or family member may not fit your financial situation.
5. Ignoring Costs
Expense ratios and applicable exit loads can affect investment outcomes.
6. Confusing SIP With a Mutual Fund Category
SIP is an investment facility or method, not a separate type of mutual fund.
7. Checking the Portfolio Too Frequently
Short-term market movements can encourage emotional decisions. A review should be linked to your goals and investment strategy.
8. Assuming Mutual Funds Guarantee Returns
Mutual fund investments are subject to market risks. Returns are not guaranteed unless specifically stated under applicable product structures, and investors should read scheme-related documents carefully.
Mutual Fund Calculator
A mutual fund calculator can help you estimate how much you may need to invest towards a financial goal.
For a SIP calculation, you generally enter:
- Monthly investment
- Expected rate of return
- Investment duration
The calculator can then provide an illustrative estimate of the potential future value. Remember that the return assumption is only an assumption. Actual mutual fund returns can be higher or lower.
Use a calculator to plan scenarios, not to predict guaranteed returns.
How Much Should You Invest in Mutual Funds?
There is no universal amount that every investor should invest. Instead, consider:
- Your monthly income
- Essential expenses
- Existing investments
- Debt obligations
- Emergency reserves
- Financial goals
- Investment horizon
- Risk tolerance
For a SIP, choose an amount that you can reasonably maintain without compromising essential financial needs. As your income changes, you can reassess the amount rather than starting with an unnecessarily large commitment.
Should Beginners Invest in Mutual Funds?
Mutual funds can be considered by beginners, but being new to investing does not mean choosing a fund based on popularity alone. A beginner should first understand:
- What the money is for
- When the money will be needed
- How much risk can be accepted
- Which category fits the goal
- What the selected fund actually invests in
- What costs apply
- How the investment will be reviewed
If you do not understand a scheme's objective or risks, take the time to understand them before investing.
Mutual Fund Investment Guide: A Simple Checklist
Before investing, ask yourself these seven questions:
1. What is my goal?
Know what you are investing for.
2. When will I need the money?
Set a realistic investment horizon.
3. How much risk can I take?
Consider both financial capacity and emotional comfort.
4. Which category fits my goal?
Choose the category before choosing the scheme.
5. Why am I choosing this particular fund?
Have a reason beyond recent returns or popularity.
6. What will it cost me?
Check expense ratio, exit load and other applicable costs.
7. When will I review it?
Review periodically based on your goals, not every time the market moves.
Frequently Asked Questions About Mutual Fund Investment
1. What is the best way to start investing in mutual funds?
A: Start by identifying your financial goal, investment horizon and risk profile. Then select an appropriate mutual fund category and compare schemes based on factors such as risk, consistency, portfolio, costs and investment strategy.
2. Is SIP better than lump-sum investment?
A: Neither is universally better. SIP involves periodic investments, while lump-sum investing puts a larger amount into the market at one time. The appropriate approach depends on your cash flow, goals, asset allocation and investment strategy.
3. Can I invest in mutual funds without a Demat account?
A: Yes. Conventional mutual fund units can generally be held without a Demat account when purchased through applicable mutual fund channels. ETFs are different because they trade on stock exchanges and generally require a trading and Demat account.
4. What is the minimum amount required to invest in a mutual fund?
A: The minimum investment varies by scheme and the transaction type. Some schemes allow relatively small investments, but there is no single minimum amount applicable to every mutual fund.
5. Are mutual funds safe?
A: Mutual funds are subject to market and scheme-specific risks. The level of risk varies across categories and individual schemes. Investors should check the scheme's Riskometer and understand the underlying risks before investing. Securities and Exchange Board of India
6. What is the difference between Direct and Regular mutual funds?
A: Both plans generally have the same underlying portfolio and fund manager, but Direct Plans do not involve distributor commissions and therefore have a lower expense ratio. Regular Plans are routed through distributors and generally have higher expenses. AMFI India
7. How do I choose a mutual fund?
A: Start with your goal, time horizon and risk profile. Then select a suitable category and compare funds based on performance consistency, risk, portfolio, expenses, strategy and other relevant factors.
8. Can I withdraw money from a mutual fund whenever I want?
A: The ability to redeem depends on the type of scheme and its applicable terms. Open-ended schemes generally allow purchases and redemptions on an ongoing basis, subject to applicable conditions. Some schemes may have exit loads or other restrictions. AMFI India
9. Do mutual funds guarantee returns?
A: No. Mutual fund returns are generally market-linked and are not guaranteed. Past performance should not be treated as an assurance of future returns.
10. How often should I review my mutual fund investments?
A: There is no need to check your portfolio every day. Review it periodically and whenever there is a meaningful change in your goals, financial situation, risk profile or the fund's investment strategy.
Conclusion
Investing in mutual funds does not begin with finding the fund that delivered the highest return last year. It begins with understanding yourself as an investor. Know your goal. Understand your time horizon. Assess your risk. Choose the right category. Then compare funds based on their objective, portfolio, performance, costs and strategy.
Whether you invest through a SIP or lump sum, a Direct or Regular Plan, the most important thing is that the investment approach makes sense for your financial goals. A mutual fund is a tool. The right investment decision comes from knowing how and why you are using it.
All efforts have been made to ensure the information provided here is accurate. However, no guarantees are made regarding correctness of data. Please verify with scheme information document before making any investment.






AMFI Registration No. 112358 | CIN: U74999MH2016PTC282153
Shepard Technologies Pvt. Ltd. (with ARN code 112358) makes no warranties or representations, express or implied, on products offered through the platform. It accepts no liability for any damages or losses, however caused, in connection with the use of, or on the reliance of its product or related services. Terms and conditions of the website are applicable.
©2026 Shepard Technologies Private Limited. All Rights Reserved